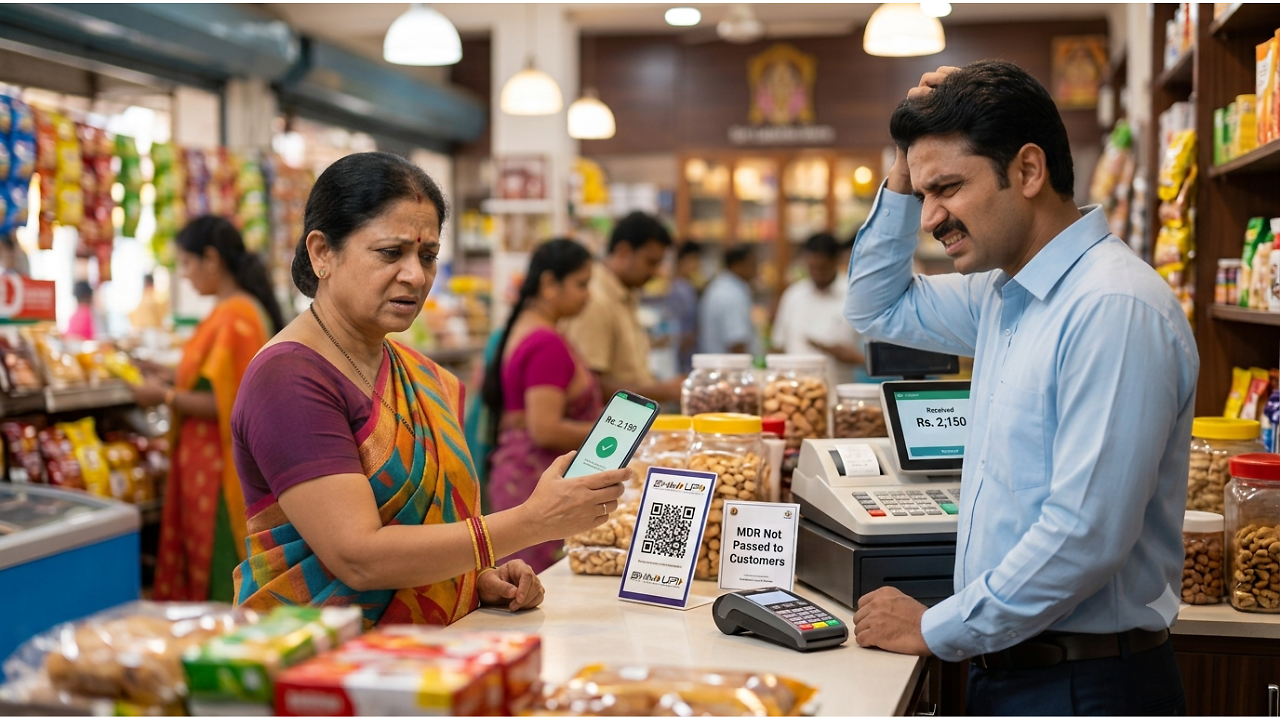
The newly announced Merchant Discount Rate (MDR) framework for Unified Payments Interface (UPI) transactions is expected to change the economics of certain digital payments, but consumers are not expected to bear the cost directly. Experts from the consumer and financial services ecosystem said the framework distinguishes between different categories of UPI transactions, with several use cases either exempted or placed under lower rates. The broader 0.4 per cent MDR applies to eligible merchant transactions above Rs 2,000, while person-to-person payments remain outside the framework.
Importantly, merchants are not permitted to directly pass the MDR on to customers.
Prof Bejon Kumar Misra, author and international expert on consumer protection policies, said consumers should not be impacted by the new MDR as long as the government’s assurance that the cost will not be passed on to them is effectively enforced.
“Consumers will not get affected with this MDR because government has assured that no burden would be passed on to the consumer. It will be zero tolerance for consumer in terms of MDR. We need to wait and watch how it will be monitored, how accountability will be there, transparency will be adopted and how RBI will intervene in terms of if there are any consumer complaints in this regard that the amount, MDR amount is being passed on to the consumer.”
Misra said the effectiveness of the framework would ultimately depend on monitoring, transparency and grievance redressal mechanisms.
“So at this present moment, I strongly feel that government is going in the right direction to assure security, to assure transparency, to assure complaint redressal and to take care of all the finer points in terms of ensuring fraudulent activities don’t happen online and to protect the consumer. This kind of a cost needs to be borne by the traders who are the intermediaries and they have to give that kind of a facility of world-class kind of an assurance in terms of quality service to the consumer out of this money which the government has proposed that this is a mandatory requirement in terms of ensuring that we are able to sustain this activity which is one of the best convenient method for transaction and world over it has been recognised what India has done. No other countries have been able to do it in the manner India has implemented. So it’s a big kind of a move and I think RBI is moving in the right direction as the regulator in proposing that this kind of a transactional cost should be borne by the providers who would profit out of this engagement in terms of providing the service to the consumer.”
0.4% MDR Does Not Apply To Every UPI Payment
Prahlad Krishnamurthi, CEO of Probe42, stressed the importance of distinguishing between one-time UPI payments and recurring mandates. “Consumers should not see their mutual fund SIPs, insurance premiums or OTT subscriptions become more expensive merely because they use UPI AutoPay, since recurring mandates are outside the prescribed MDR framework. The distinction is important because the new framework treats recurring mandates differently from one-time UPI payments. For one-time payments, the economics vary by category: insurance payments above Rs 2,000 attract a flat Rs 5 merchant charge, while capital-market transactions, including mutual funds, attract 0.02 per cent, capped at Rs 300.
“The wider 0.4 per cent MDR applies to eligible merchant payments above Rs 2,000, not to consumers or person-to-person transfers and merchants cannot pass it directly to customers. The real impact will therefore be on merchant payment economics rather than the price displayed to consumers. At scale, implementing this structure will depend on accurately identifying the business behind each transaction and classifying it under the correct merchant category. Reliable entity-level business data can help banks, payment providers and enterprises reduce misclassification, apply the appropriate rate and reconcile payment costs accurately,” he added.
This means the impact will vary depending on the nature of the transaction. While eligible merchant payments above Rs 2,000 can attract the broader MDR, certain sectors have been assigned separate rates.
For consumers, the distinction is important because the framework does not amount to a blanket fee on UPI usage.
Capital Market Transactions Get Lower MDR
Dhiraj Relli, MD & CEO of HDFC Securities, pointed to the separate treatment of capital-market transactions under the new framework. “The headlines around the new UPI charge have understandably focused on the 0.4 per cent MDR, but what deserves equal attention is the decision to carve out capital market transactions into their own category at just 0.02%, capped at Rs. 300. That’s roughly a twentieth of the standard rate, and it isn’t incidental. UPI has become the backbone of retail investing in India and it settles IPO applications, funds SIPs, and brings first-time investors from smaller towns into formal markets faster than any rail we have had before,” Relli said.
He noted, “A blanket charge across all UPI use cases would have quietly taxed that progress. This calibrated approach tells us the intent was never to burden the retail investor, but to build a sustainable funding model for UPI’s infrastructure without pricing ordinary Indians out of investing.”
Relli added that the impact on stockbroking customers should remain limited, particularly because UPI AutoPay-based SIPs fall outside the framework.
“For stock broking clients in my view, the practical impact is minimal. SIPs set up through UPI AutoPay fall outside this framework entirely, and one-time transfers will carry a cost of a few rupees at most, never more than Rs. 300. We have always believed the health of India’s capital markets depends on keeping the cost of participation low, and we are glad to see that reflected in how this policy has been designed. As an industry, we should read this not as a new cost, but as a considered decision to protect retail access to markets,” he said.
What The New UPI MDR Means For Users
The expert reactions point to three broad takeaways from the new framework.
First, consumers are not supposed to be charged MDR directly. Second, the 0.4 per cent rate does not apply universally to every UPI transaction, with different categories carrying different treatment. Third, recurring UPI AutoPay mandates and person-to-person transfers remain outside the prescribed MDR framework.
The key implementation question now will be whether merchants and payment ecosystem participants comply with the rules without indirectly transferring the cost to customers. Monitoring, transaction classification and complaint redressal will therefore remain important as the new structure takes effect from October 15.
